Atal Pension Yojana (APY) is a government-backed pension scheme, run by the Pension Fund Regulatory and Development Authority (PFRDA), aimed mainly at workers in the unorganised sector who have no employer pension. You contribute a fixed amount every month until age 60. From 60, you receive a guaranteed monthly pension of ₹1,000, ₹2,000, ₹3,000, ₹4,000 or ₹5,000, as you chose when you joined.
The idea is simple and the starting amounts are small, which is why it suits people like drivers, domestic workers, small shopkeepers and gig workers. This guide covers eligibility, how the numbers work, and the limits that every applicant should understand.
Quick answer
- Age to join: 18 to 40 years.
- Pension: ₹1,000 to ₹5,000 per month from age 60, fixed at the time of joining.
- Who can join: Indian citizens with a savings bank or post office account, an Aadhaar-linked mobile number, and who are not income tax payers. From 1 October 2022, income tax payers are not eligible to join.
- Contribution: depends on your age at joining and the pension you choose. The earlier you join, the lower the amount.
- If the subscriber dies: the spouse continues to receive the same pension, and after both, the nominee receives the accumulated corpus, which is ₹8.5 lakh for the ₹5,000 pension option.
Contribution chart
The table shows the approximate monthly contribution for the maximum pension of ₹5,000. These figures come from the PFRDA chart and are rounded. Check the current chart with your bank, because it can be revised.
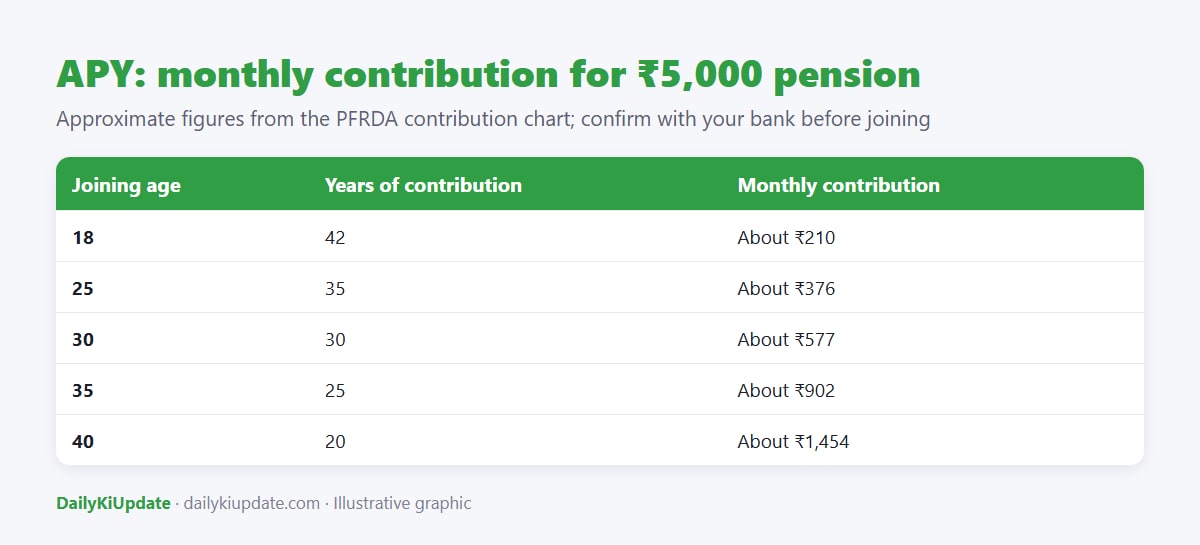
| Joining age | Monthly contribution for ₹1,000 pension | Monthly contribution for ₹5,000 pension |
|---|---|---|
| 18 | About ₹42 | About ₹210 |
| 25 | About ₹76 | About ₹376 |
| 30 | About ₹116 | About ₹577 |
| 35 | About ₹181 | About ₹902 |
| 40 | About ₹291 | About ₹1,454 |
Look at how much waiting costs. A person who joins at 18 pays about ₹210 a month for a ₹5,000 pension. Joining at 40 for the same pension costs about ₹1,454 a month, roughly seven times as much, though for fewer years.
How the pension is paid
You get the pension for life from age 60. After you, your spouse gets the same pension. After the death of both, the nominee receives the corpus accumulated at age 60 (for the ₹5,000 pension, ₹8.5 lakh). The return of the corpus is a feature that makes the scheme more attractive than a pure annuity.
How to join
- Go to the bank or post office where you have your savings account, or use net banking or mobile banking if the bank offers APY online.
- Fill in the APY registration form with your Aadhaar and mobile number, nominee details and the pension amount.
- Give an auto-debit instruction. The monthly contribution is deducted from your savings account.
- Keep your PRAN (Permanent Retirement Account Number) and the registration acknowledgement safe.
Rules you must understand before joining
- The pension amount is fixed, but it is not inflation-adjusted. ₹5,000 a month may buy much less thirty years from now. APY is a base layer, not a full retirement plan.
- Keep the account funded. Missed contributions attract a small penalty each month, and if the account stays unpaid for a long time it can be frozen, deactivated and eventually closed.
- Early exit is restricted. Exiting before 60 is generally allowed only in limited cases, such as death or a terminal illness, and the benefits are different from the full pension.
- Income tax payers cannot join since 1 October 2022. If you later become a taxpayer, check the rule on continuation with your bank.
- Tax benefits: contributions can qualify for a deduction under the rules applicable to the pension scheme, depending on the tax regime you choose. Confirm with a tax adviser.
Who should join, and who should look elsewhere?
- Good fit: workers without employer pension or EPF, between 18 and 40, with a stable small income and who value certainty over returns.
- Consider other options: if you can afford to invest more and want inflation-beating growth, compare APY with NPS or long-term investments. See our NPS vs UPS comparison for how market-linked pensions differ.
- Not eligible: income tax payers.
Frequently asked questions
What is the minimum pension under Atal Pension Yojana?
₹1,000 a month from age 60.
What is the maximum pension?
₹5,000 a month from age 60.
Can I join APY at age 41?
No. The entry age is 18 to 40.
Can I change the pension amount later?
You can generally increase or decrease the pension amount once a year in April, with the contribution changing accordingly. Ask your bank for the current process.
Is APY guaranteed by the Government?
The scheme provides a guaranteed pension amount, as described by the PFRDA. Read the official scheme document for the exact terms.
Sources to verify
- PFRDA: official Atal Pension Yojana page and contribution chart
- NPS CRA: account statements and subscriber services
Contribution figures are rounded and may change. This is general information, not financial advice.